
Blog
The Hidden Liability Gap in Private Aviation
- By: PRMA
- On: 07/21/2026 11:02:36
- In: PRMA Insights
- Comments: 0
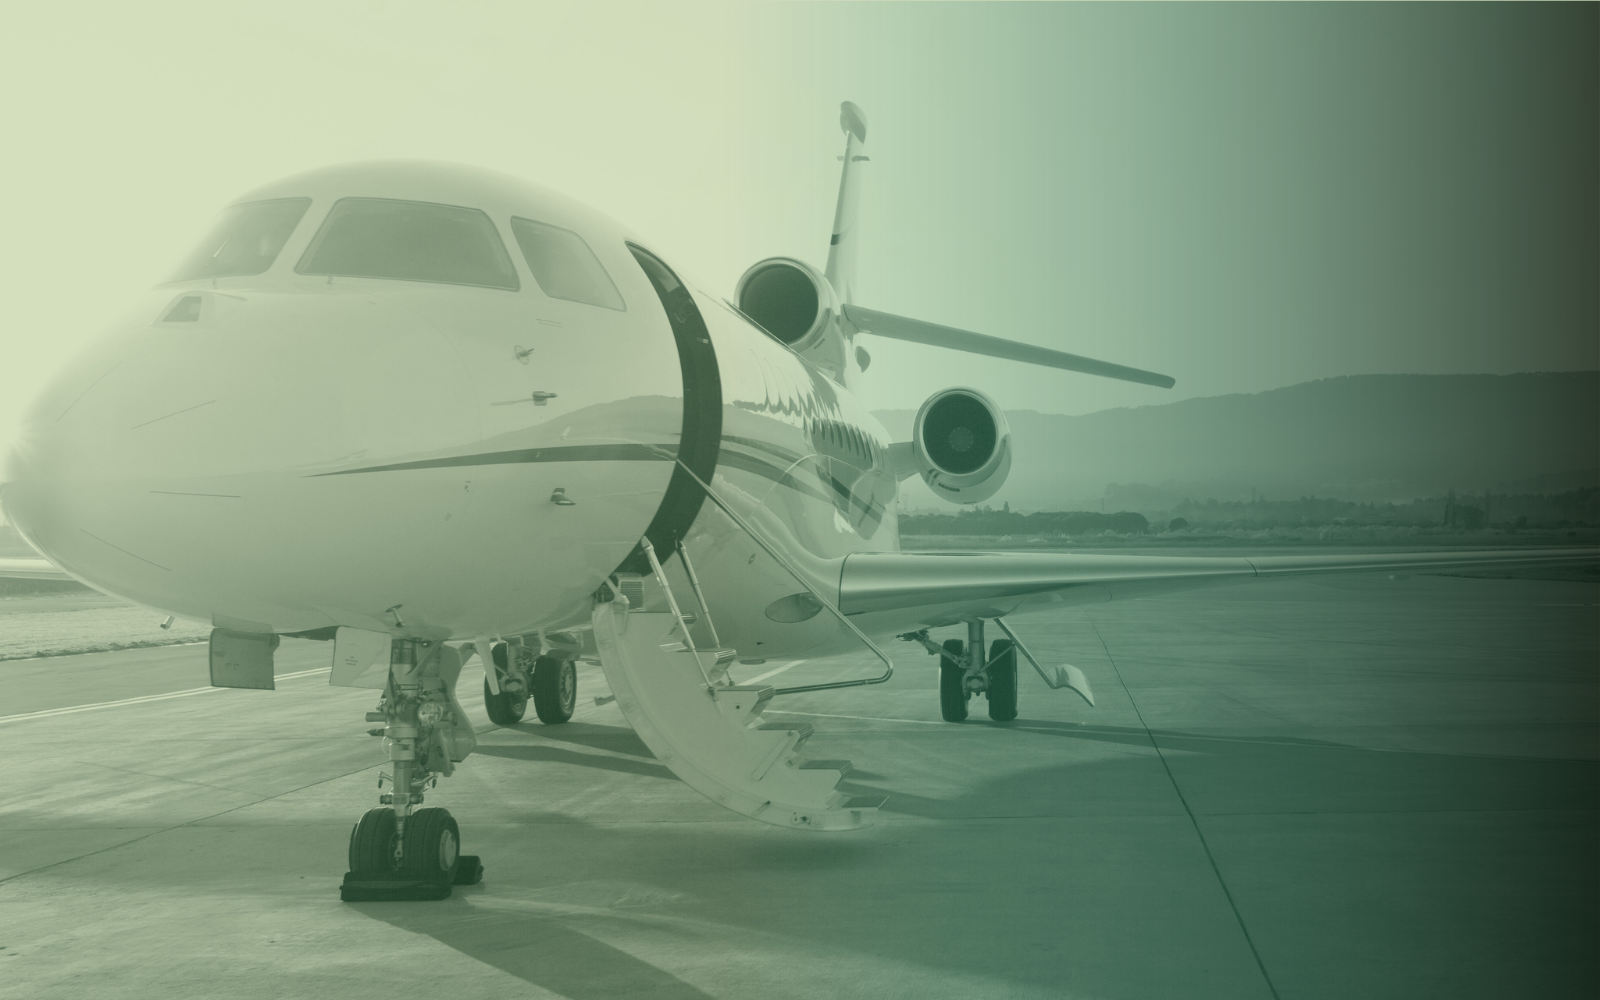
A $10 million liability limit on an aircraft that needed $100 million minimum. It's more common than you'd think.
The Hidden Liability Gap in Private Aviation
When a client takes delivery of a new aircraft, the excitement is usually the easy part. What most families, and many of their advisors, don't yet grasp is what comes next. They haven't just added an asset to their portfolio. They've taken on an entirely new layer of liability, regulation, and operational risk that standard planning was never built to cover.
Owning an aircraft isn't like owning a yacht or a classic car. It's in the air constantly, crossing jurisdictions, carrying passengers, and creating new liability every time it takes off. Aviation is also one of the most heavily regulated industries in the world, and very little of that regulatory overlap exists with the rest of a client's portfolio. For advisors used to real estate, collections, or other high-value assets, aircraft ownership is a different category of risk entirely.
The Gap Nobody Sees Coming
How an aircraft is flown changes everything about its liability profile. An owner-flown piston aircraft might carry as little as $1-2 million, often split with a $100,000 per-passenger sub-limit. An owner-flown jet raises that ceiling to roughly $5 million with strong pilot hours. A professionally flown aircraft with a dual crew, like a Gulfstream G650, can carry $200 to $750 million. The difference isn't the aircraft. It's who's flying it and how the policy is built around that.
Most families assume their personal umbrella fills in the rest. It doesn't. Personal umbrellas exclude aviation exposure, and so do most commercial umbrellas, which means the underlying aircraft policy has to carry the full weight of that risk on its own.
- Ownership structure, including any leases
- Liability exposure relative to who is flying and who is on board
- Operational oversight, from pilot warranties to safety ratings
- How the aircraft fits into the client's overall wealth strategy
Alternative flight models don't close this gap either. Fractional ownership, chartering, and dry leasing all come with an assumption of coverage that isn't automatic. In one recent case, a client dry-leasing a 13-seat jet had a $10 million liability limit on a policy that needed a $100 million minimum. He had no idea, and neither did the person who arranged the lease.
Getting this right isn't about avoiding every risk. It's about eliminating the surprises, so the coverage is already there when the unexpected happens.
Comments
There have been no comments made on this article. Why not be the first and add your own comment using the form below.
Leave a comment
Commenting is restricted to members only. Please login now to submit a comment.